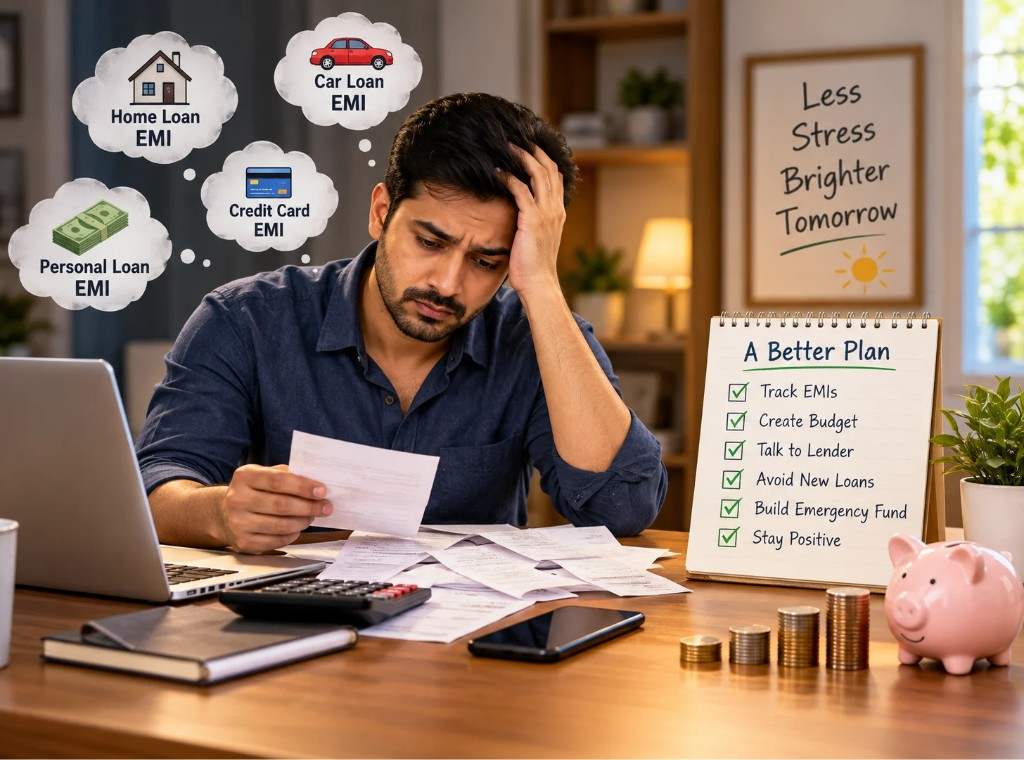
Have you ever checked your bank balance after receiving your salary and realised that most of your money is already committed to loan EMIs, household expenses, and other responsibilities?
For many salaried people in India, this situation is becoming increasingly familiar. A home loan, personal loan, vehicle loan, or credit card EMI may seem manageable individually. However, when several payments come together, even a stable monthly income can start feeling insufficient.
The real challenge is not always the amount of debt. Sometimes, it is the fear of missing a payment, disappointing your family, or losing control of your finances.
Fortunately, loan EMI stress management does not require an overnight financial transformation. Instead, it begins with understanding your situation, making practical adjustments, and taking action before anxiety turns into panic.
In this guide, The Life TrackR explores how to manage loan EMI pressure, protect your financial stability, and rebuild confidence through realistic money habits.
Why Loan EMI Stress Feels So Overwhelming
Imagine a salaried employee earning ₹55,000 per month. After paying a home loan EMI of ₹18,000, a personal loan EMI of ₹7,000, and essential household expenses of ₹24,000, only ₹6,000 remains.
Suddenly, an unexpected medical bill, vehicle repair, or family responsibility appears.
Although the person has a regular income, the financial flexibility is extremely limited. Consequently, even a small additional expense can create considerable anxiety.
This is where EMI stress begins affecting more than your bank account.
Common Signs of Loan EMI Stress
Financial pressure can appear through several everyday behaviours. For instance, you might repeatedly check your bank balance, worry about upcoming payment dates, or struggle to concentrate at work.
Similarly, some people avoid opening loan messages because they fear discovering another financial problem.
Over time, these habits may affect sleep, family communication, and emotional well-being.
However, recognising these warning signs early gives you an opportunity to regain control before the situation becomes more difficult.
1. Understand Your Complete EMI Situation
The first step towards effective loan EMI stress management is replacing uncertainty with accurate information.
Instead of thinking, “I have too many loans,” identify exactly how much you owe and when each payment is due.
Prepare a simple loan overview containing your outstanding balance, monthly EMI, interest rate, remaining tenure, and payment date.
For example:
| Loan Type | Monthly EMI |
|---|---|
| Home loan | ₹18,000 |
| Personal loan | ₹7,000 |
| 10:45–12:00Vehicle loan | ₹5,000 |
| Total monthly EMI | ₹30,000 |
If your take-home salary is ₹60,000, your EMI commitments consume 50% of your monthly income.
This does not automatically mean financial failure. Nevertheless, it indicates that your household budget may have limited room for unexpected expenses.
Practical advice: Review all active loans together rather than evaluating each EMI separately.
2. Stop Panicking and Focus on What You Can Control
When financial pressure increases, the mind often imagines the worst possible outcome.
You may worry about collection calls, damaged credit history, or the possibility of being unable to support your family.
Although these concerns deserve attention, constant worrying rarely improves your financial position.
Instead, separate the situation into two categories: things you can control and things you cannot immediately change.
You may not be able to increase your salary overnight. However, you can review expenses, contact your lender, stop unnecessary borrowing, and organise upcoming payments.
Use the 24-Hour Financial Clarity Approach
When EMI anxiety becomes intense, avoid making impulsive borrowing decisions.
First, write down the exact amount required for your next payment. Next, calculate the money available after essential expenses. Finally, identify any shortfall and the options available to address it.
This approach creates a practical starting point without pretending that the debt has disappeared.
3. Create an EMI-Friendly Monthly Budget
A realistic budget makes Loan EMI Stress Management easier by helping you balance loan repayments, household expenses, and savings.
For example, a family earning ₹60,000 per month can organise its expenses as follows:
| Expense Category | Monthly Amount | |
|---|---|---|
| Loan EMIs | ₹30,000td> | |
| Household Expenses | ₹22,000td> | |
| Emergency Savings | ₹5,000td> | |
| Personal Spending | ₹3,000td> | |
| Total | ₹60 000 |
However, this is only an example. Your budget should reflect your actual income and family responsibilities.
Prioritise essential expenses, reduce unnecessary spending, and save whenever possible. Additionally, review your budget regularly to maintain financial stability.
If your EMIs and essential expenses exceed your income, contact your lender to discuss possible repayment options.
4. Contact Your Bank Before Missing an EMI
One of the biggest mistakes during financial difficulty is avoiding communication with the lender.
However, contacting your bank or NBFC early may give you more time to explore available repayment arrangements.
Depending on your loan agreement, repayment history, and lender policies, possible options may include extending the repayment tenure, changing the payment date, or restructuring eligible loans.
Nevertheless, these arrangements are not automatic entitlements, and approval is not guaranteed.
Understand the Cost Before Accepting Changes
Extending a loan tenure can reduce your monthly EMI. However, it can also increase the total interest paid over the life of the loan.
Therefore, request a revised repayment schedule and compare the total cost before agreeing to any change.
Similarly, avoid accepting expensive short-term credit simply because it offers immediate relief.
Remember: A smaller EMI is useful only when the overall repayment arrangement is affordable and sustainable.
5. Prioritise Essential Expenses and Existing Loans
During a difficult financial period, every expense may feel equally urgent.
However, housing, food, essential utilities, medicines, and necessary commuting costs generally deserve priority in your household plan.
Next, review your loan obligations, particularly secured loans where non-payment can put pledged assets at risk.
Unsecured personal loans and credit card dues also require attention because missed payments can lead to charges, credit reporting consequences, and collection activity.
Rather than silently skipping a payment, speak with the lender about your financial situation and available options.
Furthermore, avoid sacrificing essential family needs simply to maintain an unrealistic repayment schedule.
6. Avoid Taking New Loans to Pay Old EMIs
Borrowing again may appear to be the quickest solution when a payment deadline approaches.
For instance, a new personal loan or instant loan app might offer enough money to cover an existing EMI.
Unfortunately, this can create a debt cycle in which each new repayment makes the following month more difficult.
Consequently, short-term relief may turn into long-term financial pressure.
Before considering debt consolidation or refinancing, compare the interest rate, processing charges, repayment tenure, and total amount payable.
A lower EMI alone does not prove that the new loan is cheaper.
If borrowing is genuinely necessary, deal with regulated lenders and carefully understand the contractual terms.
7. Build a Small Emergency Fund
An emergency fund may sound unrealistic when you are already struggling with EMIs.
However, even modest savings can reduce dependence on borrowing for small unexpected expenses.
Start with an achievable amount, such as ₹500 or ₹1,000 per month, provided your essential expenses and repayment obligations remain covered.
Gradually, work towards an initial emergency buffer of ₹10,000 or ₹20,000.
Later, when your finances improve, aim for a larger fund based on several months of essential household expenses.
The objective is not to build substantial savings immediately. Instead, it is to create a financial cushion that reduces future uncertainty.
8. Discuss Financial Pressure With Your Family
Loan stress often becomes more difficult when one person carries the entire emotional burden.
For example, someone may continue paying EMIs while hiding financial concerns from their spouse or other household members.
Although the intention might be to protect the family, secrecy can increase misunderstandings.
Instead, explain the situation calmly using actual numbers.
Discuss which expenses can be temporarily reduced, which financial goals can be postponed, and how household members can support the revised budget.
Importantly, avoid blaming anyone for past spending decisions.
A supportive conversation can transform financial stress from an individual burden into a shared planning responsibility.
9. Find Realistic Ways to Improve Monthly Cash Flow
Reducing expenses is useful, but there may be limits to how much a household can cut.
Therefore, improving income can also support long-term loan EMI stress management.
Depending on your skills and available time, consider freelance assignments, tutoring, part-time online work, or selling unused household items.
Additionally, review recurring subscriptions, delivery expenses, and purchases that no longer provide meaningful value.
However, avoid side-income opportunities that demand large upfront payments or promise guaranteed earnings.
Your goal should be sustainable additional cash flow, not another financial risk.
10. Protect Your Mental Well-Being During EMI Pressure
Financial difficulties can affect concentration, relationships, sleep, and confidence.
Nevertheless, your outstanding loan balance does not determine your personal worth.
Try setting aside a specific time to review finances instead of worrying about money throughout the entire evening.
Similarly, regular walks, sufficient sleep, and conversations with trusted family members may help you manage everyday stress.
If anxiety becomes persistent or seriously affects your functioning, consider seeking support from a qualified mental health practitioner.
Financial planning and emotional support can work together.
A Simple 30-Day Loan EMI Stress Management Plan
- First 7 days: List all loans, outstanding balances, EMI dates, and essential expenses.
- Next 7 days: Remove avoidable spending and prepare a realistic household budget.
- Next 7 days: Contact lenders about likely payment difficulties and compare written options.
- Final 9 days: Review progress, plan upcoming payments, and start a small emergency buffer if affordable.
This plan is designed to create clarity and momentum. If an EMI is already overdue or due sooner, contact your lender immediately rather than waiting for the scheduled review period.
Common Mistakes That Make Loan EMI Stress Worse
Several behaviours can unintentionally increase financial pressure.
Ignoring bank notifications may cause you to miss important information about charges or payment arrangements. Meanwhile, using credit cards for routine expenses without a repayment plan can create additional debt.
Similarly, making financial decisions out of embarrassment may prevent you from seeking practical help.
Comparing your lifestyle with others can also encourage unnecessary spending when your budget is already stretched.
Therefore, focus on your own financial numbers and progress rather than trying to maintain appearances.
Conclusion: Financial Stability Begins With Clarity, Not Panic
Loan repayments can feel overwhelming, especially when your salary must support both household responsibilities and long-term financial commitments.
However, loan EMI stress management becomes more practical when you stop avoiding the numbers and begin making informed decisions.
Start by understanding your complete debt situation, preparing a realistic budget, communicating with lenders, and avoiding unnecessary new borrowing.
Above all, remember that financial stability is built through consistent decisions rather than instant solutions.
At The Life TrackR, we believe that managing money is not about achieving a perfect financial life. It is about creating better habits, reducing unnecessary pressure, and moving towards greater peace of mind.
Take one practical financial step today. Your journey towards stability can begin with a simple decision.
#LoanEMIStress #EMIManagement #PersonalFinanceIndia #DebtManagement #FinancialWellness #MoneyManagement #BudgetPlanning #TheLifeTrackR
Editor’s Note: This article was originally published here: https://thelifetrackr.com/how-to-handle-loan-emi-stress-without-panic-a-practical-guide-for-indian-families/ by @Kairav and @krutika